
2012.09.30 CoStone Capital Views:
The fourth CoStone Capital Management Forum and the Launch Ceremony of the Wuhu Navigation CoStone Fund commenced on September 15. The Wuhu Navigation CoStone Fund, with a scale of over ¥600m (approx. $91.8m), is the tenth fund launched by CoStone Capital and invests in the growing SMEs. This forum focuses on the topics concerned by entrepreneurs and the investment industry, such as the macro economy, the micromanagement of enterprises and social science.
The fourth CoStone Capital Management Forum and the Launch Ceremony of the Wuhu Navigation CoStone Fund commenced on September 15. The Wuhu Navigation CoStone Fund, with a scale of over ¥600m (approx. $91.8m), is the tenth fund launched by CoStone Capital and invests in the growing SMEs. This forum focuses on the topics concerned by entrepreneurs and the investment industry, such as the macro economy, the micromanagement of enterprises and social science.
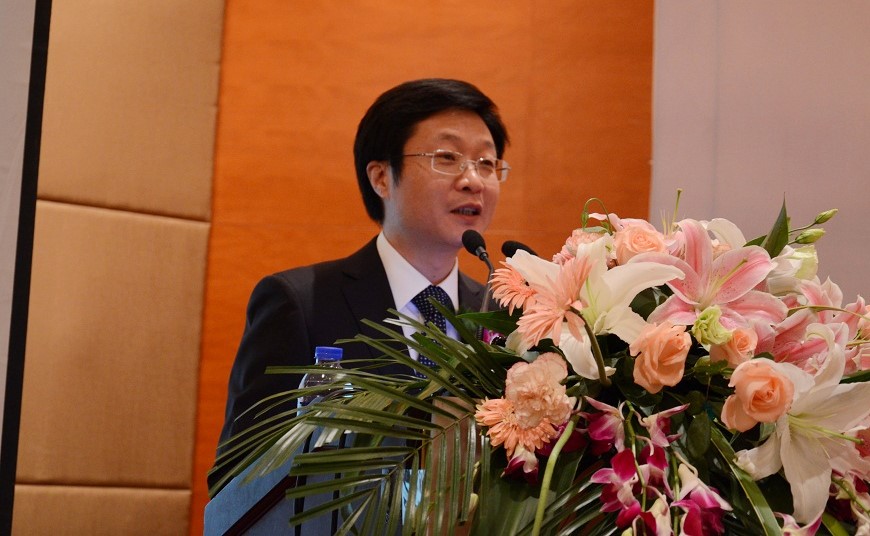
Pan Chaohui, Deputy Secretary of the Wuhu CPC Party Committee, making a speech
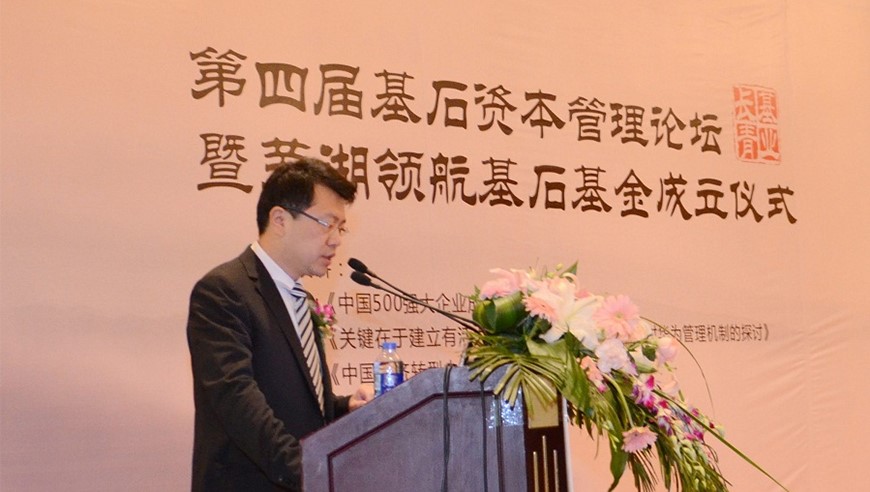
Lin Ling, CoStone Capital Partner and Manager of the Navigation CoStone Fund, introducing the fund
The launch of the Wuhu Navigation CoStone Fund was welcome among investors, although many of them were gloomy about the investment environment. Chairman Zhan Wei expressed his optimism about the environment at the fund's launch ceremony. Most of the projects that have brought high returns to CoStone Capital were invested when the macro economy was predicted to be weak and there was a decline in the capital market, said Zhang Wei.

Ha Jiming making a speech
Ha Jiming, an economist and Managing Director of Goldman Sachs Asia, corroborated Zhang Wei's opinion at the CoStone Capital Management Forum on September 15. From his analysis of the global economic trend, the upgrading of the consumption structure, the economic transformation and the aging population will fuel emerging industries in the long run. Furthermore, the valuation of the stock market is expected to go up in the fourth quarter because of an improving political environment.
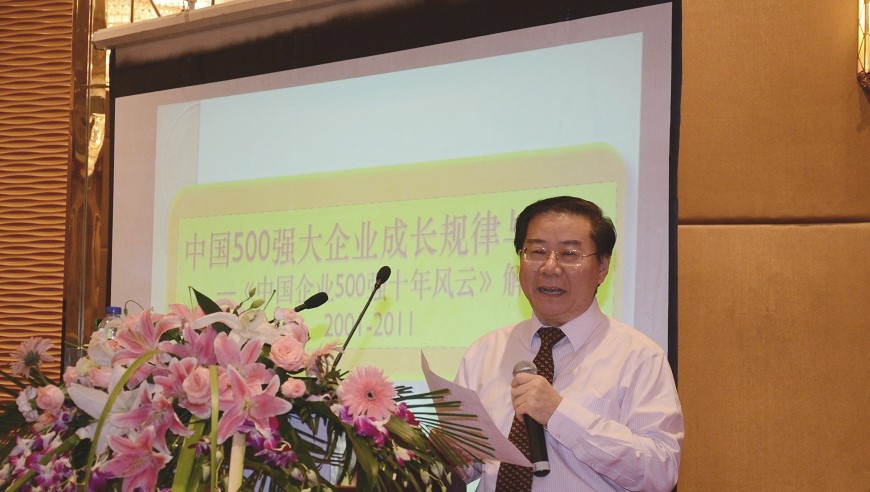
Prof. Yang Du on the Growth and Model of China's Top 500 Enterprises
Professor Yang Du at Renmin University of China lectured on the "Growth and Model of China's Top 500 Enterprises". The topic was illustrated with credible charts and figures in a critical way.
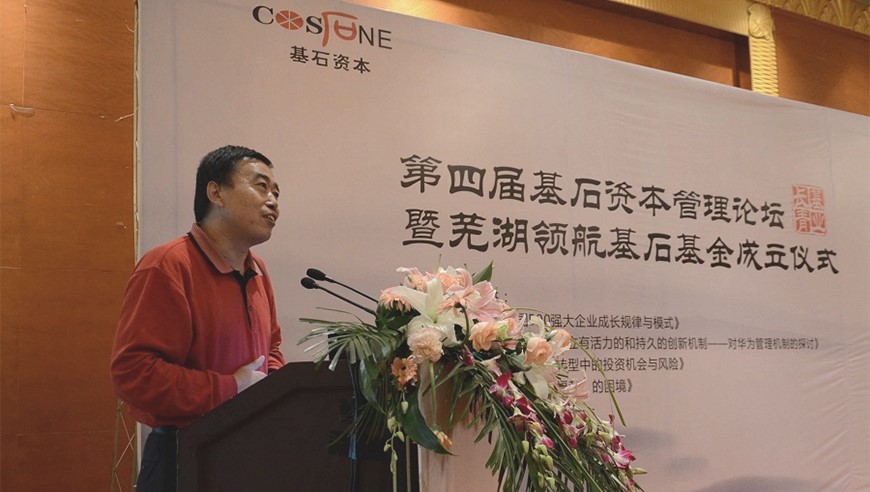
Prof. Wu Chunbo on Huawei's Culture
Professor Wu Chunbo enjoys a high reputation for his study on Huwwei's culture. As he introduced, the core of Huawei's management consists of three aspects: a performance-oriented corporate culture, a customer-oriented macro business model, and a process-oriented operation mode. Putting customers at the center is the basic culture of Huawei and the most sustainable mode of development, Prof. Wu finally added.
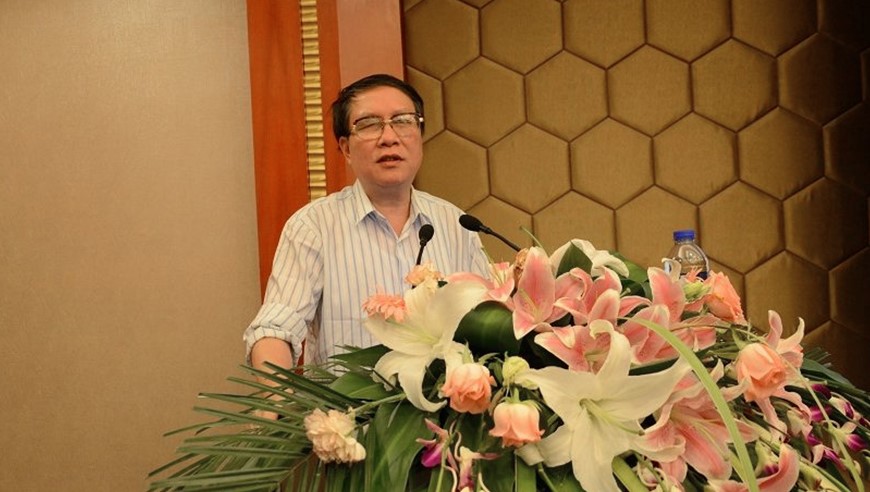
Prof. Qin Hui on Social Management
Professor Qin Hui at Tsinghua University discussed how to get out of the trap of "Negative Welfare" in his speech. He reckoned that the negative welfare problem in China is caused by "robbing the poor to feed the rich". To solve the problem, the system must be reformed. He stressed that welfare must be deemed as the citizens' right and the government's responsibility, and that the accountability system for the government should be strengthened.
Speaker
Dr. Ha Jiling
Dr. Ha Jiming is Vice Chairman and Chief Investment Strategist of the Investment Strategy Group within the Investment Management Division of Goldman Sachs Asia, focusing on macroeconomic research in China. He joined Goldman Sachs in Investment Banking Services as a managing director in 2010. Prior to joining Goldman Sachs, Dr. Ha was Chief Economist at China International Capital Corporation from 2004 to 2010. Before that, he was a senior economist at the International Monetary Fund from 1993 to 2004. He worked at the Hong Kong Monetary Authority within the IMF from 2001 to 2003 and served as the IMF resident representative to Indonesia from 1999 to 2001.
Prof. Yang Du
Yang Du is Professor and PhD Supervisor at Renmin Business School. He earned his PhD in Economics from Renmin University of China (RUC) and another PhD in Business Administration from Kobe University. He did his post-doctoral work in Management at RUC and has been teaching there since 1994. He served as Director of the Department of Business Management, Director of the Department of Theories of Management, and Director of the Department of Organization and Human Resources. His research studies the firm growing theory, knowledge management, corporate culture and enterprise ethics.
Prof. Wu Chunbo
Prof. Wu Chunbo is a leading expert at China Stone Management Consulting Group, and Professor and PhD supervisor at RUC. He also served as Dean of the Institute of Organization and Human Resources, School of Public Administration, RUC. He has published over 100 articles in journals at home and abroad and translated more than 10 foreign works. His representative works include Grasp the Future: The Planning of Modern Business Operation, Organization Design and Operation, A Course of Cases in Human Resource Management and Get out of Chaos. Prof. Wu provided design and consulting services of HR management for a dozen Chinses enterprises and organizations. As one of the drafters of the Huawei Basic Law, he has been serving as a senior corporate management advisor to Huawei since 1995.
Prof. Qin Hui
Qin Hui, a historian and economist, is Professor at the Chinese University of Hong Kong. Graduating from Lanzhou University in 1981, he is now a visiting research fellow at the Fairbank Center for Chinese Studies, Harvard University, a visiting scholar at the Harvard-Yenching Institute, Member of the Council of the China Economic History Society, and a special research fellow at the Unirule Institute of Economics. Prof. Qin used to teach history at the Department of Human and Social Sciences, Tsinghua University. His main research interests are economic history and Chinese agrarian history, with the representative work of Modernization Beyond Government and Enterprise: A Comparative Study on the History of Chinese and Western Public Welfare.
Rewritten by Jiang Xiaomei, Edited by Li Yunzhen, Du Zhixin, Wei Yiyi
Over the past year, the bull market returned, with technology leading the way.
As I said back in October 2024, the rally that began on September 24 was not merely a rebound, but a reversal. Since then, China's capital markets have undergone a broad revaluation, moving from undervaluation toward fair value.
The Shanghai Composite Index reached its highest level in a decade. The "Yi-Zhong-Tian" trio—Eoptolink, Zhongji Innolight and TFC Communication, three prominent Chinese optical communications stocks—saw their share prices multiply severalfold in a single year. Cambricon's market capitalization briefly exceeded RMB 600 billion. Elsewhere in the technology sector, triple-digit price-to-earnings ratios and valuations exceeding RMB 10 billion became commonplace.
Some investors were greedy; others, fearful. Still others asked me: Are technology stocks in a valuation bubble?
My answer is that what we are witnessing is the hunger and anxiety of an era, reflected in the capital markets. Once you understand this, the current fervor for technology investing is no longer difficult to explain.
Investment has nothing to do with macroeconomics, but everything to do with geopolitics.
China-US relations will shape the investment landscape for decades to come. Geopolitics has played a major role in shaping the hunger and anxiety of our times, fundamentally reshaping the way we invest.
What, then, lies at the heart of China's hunger and anxiety?
The Fourth Industrial Revolution is already underway, yet China has not fully overcome the technological shortcomings left by the Third. There is no time to lose.
This is why some people wonder: Why do Chinese computing chip companies command such high valuations when their technologies still lag so far behind NVIDIA's? Why does NVIDIA trade at just 50 times earnings, while a company hailed as "China's answer to NVIDIA" commands a multiple of 300?
To me, this gets the logic exactly backward.
It is precisely because these companies cannot catch up with NVIDIA in the near term that they command a higher strategic premium. The wider the technological gap, the greater the strategic value.
The further something lies beyond our reach, the stronger our hunger. The harder it is to catch up, the deeper our anxiety. If China were to achieve a complete breakthrough in computing chips one day, valuations might actually come down.
Where can one find China's most spectacular natural landscapes?
Much of the answer, I believe, lies in and around the Hengduan Mountains: the Meili Snow Mountains, Jade Dragon Snow Mountain, Mount Gongga, Mount Siguniang, Jiuzhaigou, and many others. Vast differences in elevation and deep fault lines have given rise to landscapes of extraordinary grandeur.
Hard-tech investing follows a similar logic.
Technological gaps, discontinuities in capabilities, and missing links in industrial systems: a leap in difficulty brings a leap in valuation, and a successful breakthrough can, in turn, bring a leap in returns.
This logic extends well beyond computing chips. It is equally evident in memory semiconductors, commercial spaceflight, and other sectors where China still faces substantial technological gaps with other countries.
It was precisely this conviction that led CoStone Capital, starting in 2016, to decisively focus its investments on three areas: hard tech, emerging industries, and life sciences and healthcare. In this context, "hard tech" refers specifically to important industries in which China faces a technological gap with the United States.
Thanks to this forward-looking strategy, CoStone Capital established an early presence across the full value chains of key sectors, including semiconductors, artificial intelligence, and robotics.
Looking ahead, the frontiers of technological progress and industrial upgrading are boundless. Nor can the gaps in hard technology be closed overnight. The twin windows of opportunity presented by technological innovation and the development of homegrown alternatives to foreign technologies have only just begun to open.
The road ahead is long, but the future holds immense promise.
As an investment firm, CoStone Capital will continue to invest where the hunger and anxiety of each era run deepest, move forward with the tensions that shape our times, and extend our reach toward the most challenging—and most important—frontiers.
Spring 2026