CN

Our Firm

1127.jpg

Introduction

CoStone Capital is a venture capital and private equity investment institutions in China. Its core team boasts over 20 years of investment management experience. Headquartered in Shenzhen, the company has branches in Beijing, Shanghai, Hefei, Nanjing, Changsha, Wuhan, Hong Kong, and Silicon Valley. CoStone Capital manages approximately 90 billion RMB in total assets, spanning various types such as angel investment, VC, PE, mergers and acquisitions, and private placements, covering all stages of a company's lifecycle.


Adhering to the investment philosophy of “Concentrated investment and customized services",CoStone Capital has cultivated and established numerous industry leaders and niche market champions in fields such as hard technology, emerging industries, life sciences, and healthcare, achieving sustained, stable, and excellent investment returns.


ab2.jpg

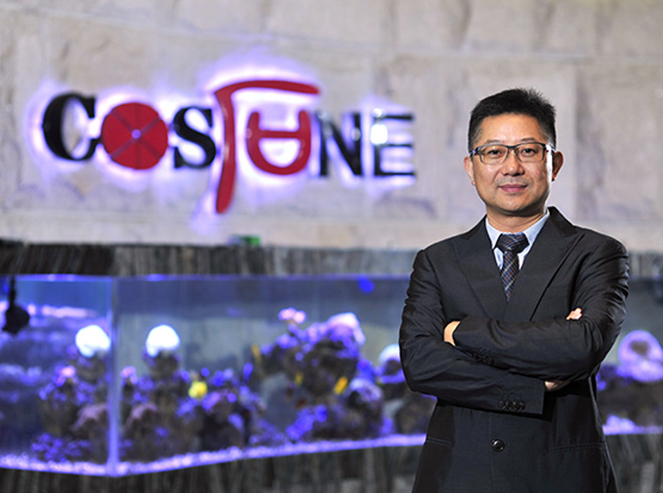
Investing in the Hunger and Anxiety of Our Times

———Greeting from the Chairman

Investment
Methodology

20210428191954767.jpg

22 Investment Rules
of Costone Capital

    • 01Fear is born in the blindness of following trends and buzzwords of investment, instead of the macro economy.
    • 02In spite of the capricious macro economy, our investment should flow in excellent enterprises in the new economy. We are investing on the real enterprises and entrepreneurs instead of the industry.
    • 03 The stock market is not a bell-weather for the macro economy. The tendency in the capital market will not be always in line with that of the macro economy in the next five to ten years. It is also true between the trends of stock prices and enterprise performance.
    • 04 Growth potential and value are paramount indicators. Growth potential guards against the uncertainties in the economy and markets. Value determines abnormal returns.
    • 05The original, world-class and platform-level technology can yield high value like a solid foundation can support a skyscraper.
    • 06 An independent IPO in A share is seen as a crucial factor. IPO in Hong Kong or the United States, stock-for-stock merger, acquisition and delisting will affect our returns on investment. Different IPO exits and value systems are essential to our returns and should be taken into consideration in the first place.
20210428192301185.jpg

22 Investment Rules
of Costone Capital

    • 07 Margin of safety is more important than profits. Irrational prosperity of the capital market is an unexpected gift. Margin of safety is the true power source of compound interests.
    • 08The enterprises with a margin of safety worth a high position of investment. One should not expect more when doing the least. Investment should have a priority.
    • 09 Investment counts on holistic judgement and three-dimensional thinking. They enable a and essential and comprehensive understanding on corporate behaviors and capital markets, or you will never see the whole picture. Holistic judgement and three-dimensional thinking combined will generate steady profits from 10-year or 20-year projects.
    • 10 Investment is not a science but an embodiment of cognitive capacity. The right investment needs strong comprehension. One may not fully comprehend what he feels, but he can definitely feel what he fully comprehends.
    • 11 Combinational investment, diversified portfolio and trend investing are not working in both primary and secondary markets. Therefore, we will not stick to only one industry.
20210428192418249.jpg

22 Investment Rules
of Costone Capital

    • 12Investment depends on commonsense. Don’t be thrown by the appearance of an enterprise. It is likely a monster in disguise.
    • 13 An enterprise is an organic body. Financial indicators are not the only approach to comprehend corporate behaviors. The reports of brokers are now overwhelmed with irresponsible optimism.
    • 14 Not all enterprises that CoStone invested boasted entrepreneurship, but those who did brought CoStone time-enduring and extraordinary profits.
    • 15 Be careful about those enterprises which dabble in different fields, play at the capital market, or refuse to make long-term investment on R&D and the building of mechanisms.
    • 16 All investment holding companies are troublemakers. If we don’t value corporate governance, it will backfire.
    • 17 Be kind those entrepreneurs who have devoted themselves for us and be harsh to those frauds who create information asymmetry on purpose. For those who commit the crime of frauds and duty encroachment, we must hunt them down.
20210428192708008.jpg

22 Investment Rules
of Costone Capital

    • 18The corporate governance of state-owned enterprises is underperformed. We will not participate in the mixed ownership reforms of those enterprises which the executives do not hold shares, corporate governance has not been improved or have trouble with securitization in domestic market. We will prioritize the enterprises which have shifted the control power.
    • 19 The century-old enterprises share one recipe——they are the organizers of an industry chain instead of merely a producers of a product. CoStone vowed to be the organizer of the industrial chain for equity investment.
    • 20 Profits are the natural outcomes instead of our original goals. CoStone will remain compassionate, aspiring, ambitious and responsible. As a qualified enterprise, we provide a platform for talented colleagues who share the same values and eliminate unqualified ones.
    • 21The mission of C-Level Executives is to create, find and clinch crucial deals.
    • 22 Angel investment, part of CoStone’s charitable campaigns, should be operated as an enterprise and should be commercial, in order to increase investment and benefit more entrepreneurs. We are doing the same in other investment. Investment is how we provide capital for all industries and make contribution to the society. Our new mission is to introduce public capitals to private sector.

Culture and Values


Talent is our most valuable asset;
We are engaged in a team work, individual heroism will not be encouraged;
Employees must have honesty, integrity and sense of responsibility, and refuse any defects in professional ethics;
To assist enterprises to build core competitiveness and achieve long-term success is our cause The foundation of existence;
We strive to pursue financial return and social value beyond it to create "beauty" Things of the world;
We resolutely abandon the speculation that causes harm to customers and enterprises and destroys value;
We have an obligation to create returns to our customers;
We share success with employees, customers and enterprises;
We must always focus on the asset management industry, which is our core competence.

Honors

Association Accreditation
Institutional Awards
Media Awards

Stay up to date

SIGN UP FOR UPDATES

CoStone Capital | 2026 New Year Message


Over the past year, the bull market returned, with technology leading the way.

As I said back in October 2024, the rally that began on September 24 was not merely a rebound, but a reversal. Since then, China's capital markets have undergone a broad revaluation, moving from undervaluation toward fair value.

The Shanghai Composite Index reached its highest level in a decade. The "Yi-Zhong-Tian" trio—Eoptolink, Zhongji Innolight and TFC Communication, three prominent Chinese optical communications stocks—saw their share prices multiply severalfold in a single year. Cambricon's market capitalization briefly exceeded RMB 600 billion. Elsewhere in the technology sector, triple-digit price-to-earnings ratios and valuations exceeding RMB 10 billion became commonplace.

Some investors were greedy; others, fearful. Still others asked me: Are technology stocks in a valuation bubble?

My answer is that what we are witnessing is the hunger and anxiety of an era, reflected in the capital markets. Once you understand this, the current fervor for technology investing is no longer difficult to explain.

Investment has nothing to do with macroeconomics, but everything to do with geopolitics.

China-US relations will shape the investment landscape for decades to come. Geopolitics has played a major role in shaping the hunger and anxiety of our times, fundamentally reshaping the way we invest.

What, then, lies at the heart of China's hunger and anxiety?

The Fourth Industrial Revolution is already underway, yet China has not fully overcome the technological shortcomings left by the Third. There is no time to lose.

This is why some people wonder: Why do Chinese computing chip companies command such high valuations when their technologies still lag so far behind NVIDIA's? Why does NVIDIA trade at just 50 times earnings, while a company hailed as "China's answer to NVIDIA" commands a multiple of 300?

To me, this gets the logic exactly backward.

It is precisely because these companies cannot catch up with NVIDIA in the near term that they command a higher strategic premium. The wider the technological gap, the greater the strategic value.

The further something lies beyond our reach, the stronger our hunger. The harder it is to catch up, the deeper our anxiety. If China were to achieve a complete breakthrough in computing chips one day, valuations might actually come down.

Where can one find China's most spectacular natural landscapes?

Much of the answer, I believe, lies in and around the Hengduan Mountains: the Meili Snow Mountains, Jade Dragon Snow Mountain, Mount Gongga, Mount Siguniang, Jiuzhaigou, and many others. Vast differences in elevation and deep fault lines have given rise to landscapes of extraordinary grandeur.

Hard-tech investing follows a similar logic.

Technological gaps, discontinuities in capabilities, and missing links in industrial systems: a leap in difficulty brings a leap in valuation, and a successful breakthrough can, in turn, bring a leap in returns.

This logic extends well beyond computing chips. It is equally evident in memory semiconductors, commercial spaceflight, and other sectors where China still faces substantial technological gaps with other countries.

It was precisely this conviction that led CoStone Capital, starting in 2016, to decisively focus its investments on three areas: hard tech, emerging industries, and life sciences and healthcare. In this context, "hard tech" refers specifically to important industries in which China faces a technological gap with the United States.

Thanks to this forward-looking strategy, CoStone Capital established an early presence across the full value chains of key sectors, including semiconductors, artificial intelligence, and robotics.

Looking ahead, the frontiers of technological progress and industrial upgrading are boundless. Nor can the gaps in hard technology be closed overnight. The twin windows of opportunity presented by technological innovation and the development of homegrown alternatives to foreign technologies have only just begun to open.

The road ahead is long, but the future holds immense promise.

As an investment firm, CoStone Capital will continue to invest where the hunger and anxiety of each era run deepest, move forward with the tensions that shape our times, and extend our reach toward the most challenging—and most important—frontiers.

Spring 2026

Stay up-to-date

Email Alerts
To receive newsletter from CoStone Capital, sign up below.

Submit