
2012.12.01 CoStone Capital Views:
CoStone Annual Meeting 2012 kicked off at MGM Grand Sanya, Hainan on March 23, with nearly 300 investors and entrepreneurs being present.
March 26, 2012
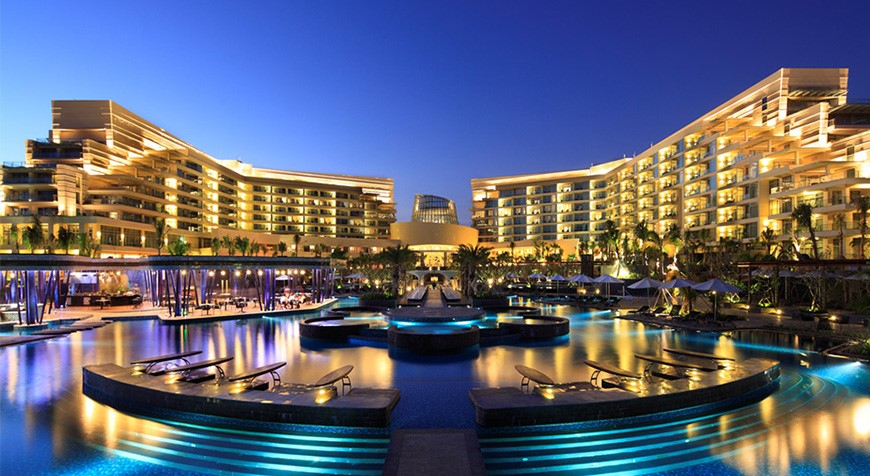
MGM Grand Sanya
The three-day annual meeting consists of performance reporting, Chairman Zhang Wei's keynote speech and lectures of experts in management.
On the first day, an investor conference for four funds managed by CoStone Capital including the Guangzhou Fund and the CoStone Everest Fund was held. In the conference, CoStone Capital reported to the investors on the performance of the funds and won high praise for the team's excellent expertise and risk control ability.
Zhang Wei made a speech on the Situation and Strategies of Equity Investment. He observed a decline in the returns of Pre-IPO investment. Against the backdrop, CoStone Capital is going to launch a late-stage VC fund investing in high-growth enterprises at the early stage, with a target of ¥600m (approx. $91m). CoStone Capital, as the fund manager, promises to commit to the fund at a high proportion, which reflects that it shares a great many common interests with the investors. As a result, moral hazards can be prevented and self-discipline strengthened, said Chairman Zhang.
The next two days witnessed the CoStone Master Forum.
Professor Sun Liping at Tsinghua University made a speech on the Economic Development & Social Progress. In his opinion, China needs a social progressive movement which enables the middle class to grow larger so as to stimulate the consumer demand for durable goods.
Professor Shi Wei at Renmin University of China lectured on the Enterprise Transformation and the Capacity Gap. He called on the enterprises to hire and cultivate more young people or graduates and to discover, stimulate and enhance the entrepreneurial capacity of a tiny fraction of them. Furthermore, enterprises should establish a long-term partnership with employees and foster a culture of common growth, added Prof. Shi.
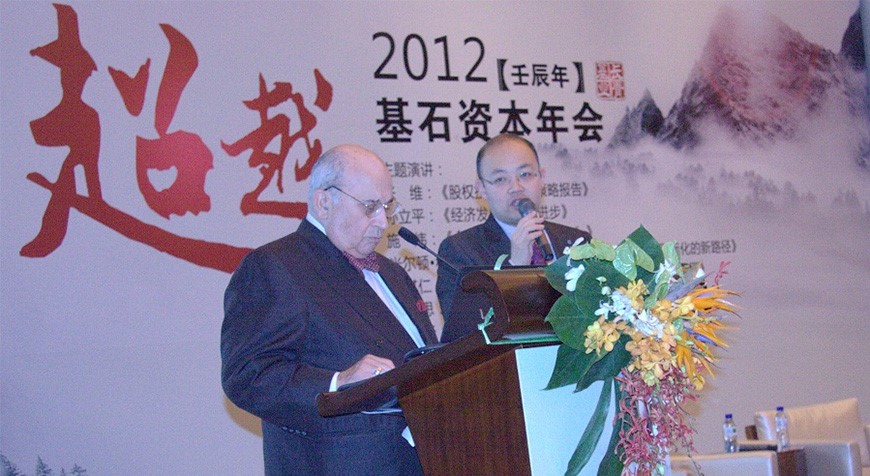
Prof. Philip Kotler making a speech
Professor Philip Kotler, a world-famous marketing master, made a speech on Economic Woes in the US and Europe and New Opportunities Arising from the Internationalization of Chinese Enterprises. He advised Chinese enterprises to seek M&A opportunities with hidden champions in the American manufacturing sector for technological and brand upgrading.
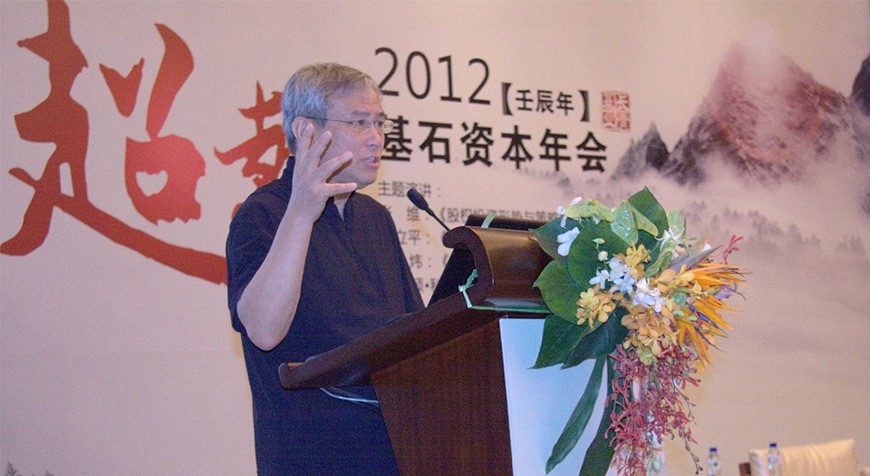
Prof. Zhou Qiren making a speech on Market Base
Professor Zhou Qiren prioritized the issue of property rights in his speech. He believed that, to raised the income of farmers, the government should clarify and protect their property right rather than only offer subsidies and tax cuts.
Wu Si, a historian, analyzed the Chinese history since the Qin dynasty and proposed a new view of history for explaining the issues of public concern throughout the history.
Professor Peng Jianfeng, Chairman of China Stone Management Consulting Group, talked about the mechanism building and the practice of Midea. From his perspective, Midea's mechanism, which features high performance and the sharing spirit, has contributed to its success. In other words, Midea values the contribution of employees and shares benefits with them.
Professor Bao Zheng at Renmin University of China (RUC) shared his views of Chinese-style management. As he said, enterprises should aim for sharing benefits and the future with customers on the basis of satisfying their needs. Moreover, he emphasized that it is the manager who should be relied on to run the business and create a common belief for the enterprise.
Speaker
Prof. Sun Liping
Sun Liping is Professor and PhD Supervisor at the Department of Sociology, School of Social Sciences, Tsinghua University. His research focuses on social modernization, changes of social structure in China and sociology of transformation. He was named Person of the Year for Public Interests by South Reviews in 2006.
Prof. Shi Wei
Shi Wei is a researcher and Chief Consultant at the Finance and Securities Institute of RUC. He has been engaged in enterprise management consulting since 1995, specializing in marketing and enterprise strategy. He has served TCL, Midea Group, Giti Tire, Motorola, Liuhe Group, Robust Group, CIMC, Telling Telecom and SPD Bank. He also provides management trainings for many enterprises in China, which have been well received.
Prof. Philip Kotler
Philip Kotler is Professor Emeritus of Marketing at the Kellogg School of Management, where he held the S.C. Johnson & Son Professorship of International Marketing. He received his master's degree from the University of Chicago and his PhD from MIT, both in Economics. He did post-doctoral work in Mathematics at Harvard University and in behavioral science at the University of Chicago. Prof. Kotler has consulted for such companies as IBM, General Electric, AT&T, Honeywell, Bank of America, Merck and others in the areas of marketing strategy and planning, marketing organization and international marketing. He has been Chairman of the College of Marketing of the Institute of Management Sciences, Director of the American Marketing Association, Trustee of the Marketing Science Institute, Director of the MAC Group, a former member of the Yankelovich Advisory Board, and a member of the Copernicus Advisory Board. He is Member of the Board of Governors of the School of the Art Institute of Chicago and Member of the Advisory Board of the Drucker Foundation.
Prof. Zhou Qiren
Zhou Qiren, a famous economist, is Professor of Economics and Former Dean of National School of Development at Peking University. He received his PhD degree from the University of California Los Angeles (UCLA). He served as a member of the Monetary Policy Committee of the People's Bank of China during 2010-2012. He is a member of the Expert Committee of National Development Planning for the 13th and 14th Five Year Plan, Member of Shanghai Decision-making Advisory Committee, and Member of Entrepreneur Advisory Meeting of Hainan Provincial Government. His research focuses on property rights and contracts, firms and market Organization, monetary and exchange rate, and reform and innovation. He has been rated as the Most Popular Professor Among Students at Peking University since 1997.
Wu Si
Wu Si is a well-known writer, journalist and historian. In 1982, he graduated from the School of Liberal Arts, Renmin University of China and became Deputy Director of the Editorial Office of Farmers’ Daily. He served as Vice President and Editor-in-chief of the Chinese edition of The Bridge sponsored by the All-China Journalists' Association in 1993, and Vice President and Executive Editor of Chinese National Academy of Arts in 1996. His representative works include Chen Yonggui's Ups and Downs in Zhongnanhai: An Experiment with Changing China and Hiden Rules: True Games in Chinese History.
Prof. Peng Jianfeng
Peng Jianfeng is Professor and Supervisor at Renmin University of China, Chairman of China Stone Management Consulting Group, Deputy Director of China Enterprise Confederation Management Consulting Committee, Vice President of Beijing Enterprise Directors Association, and a famous management consulting expert in China. Prof. Peng used to be Vice President of the School of Labor and Human Resources of RUC. He has been engaged in the consulting and research work on HR management and corporate culture for a long time. He also provides consulting services for enterprises. He has been hired as a senior management consultant and a team leader by Huawei and TCL successively. The team led by him has consulted for dozens of famous enterprises, with the results of Huawei Basic Law, OCT Charter, TCL: Defeat Scale with Speed, Samsung (China) Culture and Dongfeng Nissan Programme of Action.
Prof. Bao Zheng
Prof. Bao Zheng received his PhD degree in Economics from Renmin University of China, and now is Professor and PhD Supervisor at Renmin Business School. He is a famous expert of enterprise management consulting in China, having created many famous cases, such as Huawei Basic Law and TCL: Defeat Scale with Speed. He has served as senior management consultant of Huawei (1995), TCL (1998), XJ Group (1999), Baisha Group (2002) and Hongta Group (2004).Over the past year, the bull market returned, with technology leading the way.
As I said back in October 2024, the rally that began on September 24 was not merely a rebound, but a reversal. Since then, China's capital markets have undergone a broad revaluation, moving from undervaluation toward fair value.
The Shanghai Composite Index reached its highest level in a decade. The "Yi-Zhong-Tian" trio—Eoptolink, Zhongji Innolight and TFC Communication, three prominent Chinese optical communications stocks—saw their share prices multiply severalfold in a single year. Cambricon's market capitalization briefly exceeded RMB 600 billion. Elsewhere in the technology sector, triple-digit price-to-earnings ratios and valuations exceeding RMB 10 billion became commonplace.
Some investors were greedy; others, fearful. Still others asked me: Are technology stocks in a valuation bubble?
My answer is that what we are witnessing is the hunger and anxiety of an era, reflected in the capital markets. Once you understand this, the current fervor for technology investing is no longer difficult to explain.
Investment has nothing to do with macroeconomics, but everything to do with geopolitics.
China-US relations will shape the investment landscape for decades to come. Geopolitics has played a major role in shaping the hunger and anxiety of our times, fundamentally reshaping the way we invest.
What, then, lies at the heart of China's hunger and anxiety?
The Fourth Industrial Revolution is already underway, yet China has not fully overcome the technological shortcomings left by the Third. There is no time to lose.
This is why some people wonder: Why do Chinese computing chip companies command such high valuations when their technologies still lag so far behind NVIDIA's? Why does NVIDIA trade at just 50 times earnings, while a company hailed as "China's answer to NVIDIA" commands a multiple of 300?
To me, this gets the logic exactly backward.
It is precisely because these companies cannot catch up with NVIDIA in the near term that they command a higher strategic premium. The wider the technological gap, the greater the strategic value.
The further something lies beyond our reach, the stronger our hunger. The harder it is to catch up, the deeper our anxiety. If China were to achieve a complete breakthrough in computing chips one day, valuations might actually come down.
Where can one find China's most spectacular natural landscapes?
Much of the answer, I believe, lies in and around the Hengduan Mountains: the Meili Snow Mountains, Jade Dragon Snow Mountain, Mount Gongga, Mount Siguniang, Jiuzhaigou, and many others. Vast differences in elevation and deep fault lines have given rise to landscapes of extraordinary grandeur.
Hard-tech investing follows a similar logic.
Technological gaps, discontinuities in capabilities, and missing links in industrial systems: a leap in difficulty brings a leap in valuation, and a successful breakthrough can, in turn, bring a leap in returns.
This logic extends well beyond computing chips. It is equally evident in memory semiconductors, commercial spaceflight, and other sectors where China still faces substantial technological gaps with other countries.
It was precisely this conviction that led CoStone Capital, starting in 2016, to decisively focus its investments on three areas: hard tech, emerging industries, and life sciences and healthcare. In this context, "hard tech" refers specifically to important industries in which China faces a technological gap with the United States.
Thanks to this forward-looking strategy, CoStone Capital established an early presence across the full value chains of key sectors, including semiconductors, artificial intelligence, and robotics.
Looking ahead, the frontiers of technological progress and industrial upgrading are boundless. Nor can the gaps in hard technology be closed overnight. The twin windows of opportunity presented by technological innovation and the development of homegrown alternatives to foreign technologies have only just begun to open.
The road ahead is long, but the future holds immense promise.
As an investment firm, CoStone Capital will continue to invest where the hunger and anxiety of each era run deepest, move forward with the tensions that shape our times, and extend our reach toward the most challenging—and most important—frontiers.
Spring 2026