
2019.04.30 Source: Shenzhen Special Zone Daily Views:
During the CoStone Capital Annual Conference on April 28th, Chairman Zhang Wei stated that China's upcoming Science and Technology Innovation Board (STIB) will serve as another great practice of China's strategy of asymmetric competition in the financial market. This strategy is similar to China's industrial policies from 2000 to 2010 when the Chinese government selectively supported domestic telecommunications operators and equipment manufacturers, such as Huawei, in their competition against companies like Cisco. It was in this context that Huawei emerged in China.
Zhang Wei believes that both the development of a nation and its enterprises have standard answers. Regarding competition between nations, the economic strength and vitality of the United States, for instance, are closely related to its highly developed system of direct financing. For example, the number of effective intellectual property rights owned by the United States is similar to that of the European Union, but the sales revenue of high-tech industries in the United States is four times greater than that of the EU. The difference lies in the fact that the financing system driven by capital markets greatly facilitates innovation and entrepreneurship throughout society, whereas a financing system dominated by banks has the opposite effect. Behind this difference lies the monumental role played by NASDAQ. China is currently launching the STIB, and the timing is opportune. The STIB will be the engine for China's next round of innovation in the economy.
"Asymmetric competition refers to the competition in a market featuring asymmetrical limitations and incentives, whereby companies with vastly different strengths compete in unequal or different ways. This competition seeks to answer an increasingly important and urgent question: should small and disadvantaged local companies, operating under the background of economic globalization, market openness, and the trend of monopolistic concentration in various industries, strive to grow? And if so, how?" said Zhang Wei.
The STIB will be the engine for China's next round of innovation economy.
As an investor who has been actively involved in the venture capital industry for the past 18 years, Zhang Wei has deep insight into the environment for the development of Chinese technology enterprises. From the perspective of the relationship between the financial market and innovation, China primarily relies on indirect financing through bank loans, with a low proportion of direct financing. Direct financing accounts for about 20% in China, while in the United States, it accounts for approximately 70% to 80%. Thus, China's level of direct financing lags far behind that of the United States.
Innovation is highly correlated with direct financing, with the equity market being the most crucial component of direct financing. Professor Tian Xuan from Tsinghua University has found through research that the development of the equity market can promote innovation for enterprises with a high degree of external financing reliance, while the development of the credit market hinders innovation. For high-tech intensive industries, the development of the equity market can foster innovation for enterprises, while the credit market has the opposite effect. The conclusion is that there is a positive correlation between innovative patents and the development of the equity market, and a negative correlation with the development of the credit market.
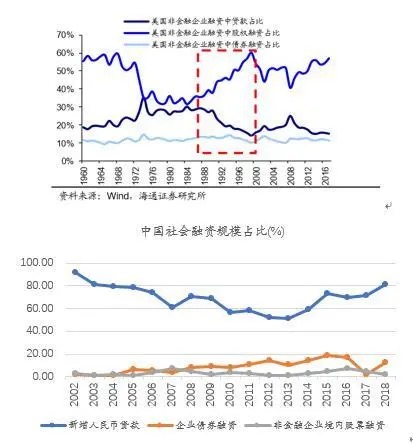
China's level of direct financing accounts for about 20%, significantly lower than the 70%-80% in the United States. Bank loans remain the primary means of financing.
The STIB of the Shanghai Stock Exchange focuses on supporting industries such as the new generation of information technology, high-end equipment, new materials, new energy, energy conservation and environmental protection, and biomedicine. It aims to promote the deep integration of the internet, big data, cloud computing, artificial intelligence, and manufacturing industry. Currently, apart from a few areas such as the internet, artificial intelligence, big data, and new energy batteries, where the development stage between China and the United States is relatively close, the majority of the technology sectors supported by the STIB are traditional tech fields in which China lags far behind the West. In these traditional hard-tech sectors with huge gaps between China and the West, it has been quite difficult to:
- Obtain loan support from banks;
- List domestically due to a lack of scale and profitability, leading to a lack of active investment from most institutions;
- Gain recognition from overseas capital markets when listing abroad due to a vast disparity in size compared to mature market competitors, resulting in no valuation premium or liquidity and making it nearly impossible to truly raise funds.
With the introduction of the STIB, it will:
- Directly expand the investment boundaries and tolerance of arbitrage institutions in the market, greatly enhancing the direct financing capability for original and innovative technology companies, thereby accelerating the development of original hard-tech in China;
- Effectively guide domestic institutions, especially RMB funds, to actively invest in smaller and more dynamic SMEs;
- The registration-based system reform contributes to increasing the financing scale and improving the support efficiency for SMEs in the capital market;
- Require enterprises to enhance their own original technological capabilities.
The STIB and the registration-based system'slaunch will help alleviate the enormous financial pressure faced by domestic technology companies in their early stages of development and extend the survival period for these enterprises.
NASDAQ's assistance in helping the United States win the US-Japan trade war
Looking at the competition between the United States and Japan further reinforces this point. In the 1970s and 1980s, when it seemed that Japan's economy would surpass that of the United States, the key factor that allowed the United States to surpass Japan was the economic transformation brought about by the development of internet technology. NASDAQ played a crucial role in this transformation by channeling funds into the technology industry, while Japan made serious mistakes in its financial industry policies. Following the Plaza Accord, the burst of the real estate bubble, and the double blow of the trade conflict, Japan's economy was completely knocked down.
In comparison, NASDAQ actively supported small businesses when it was established, and it mutually supported Silicon Valley. This solidified the United States' significant advantage in the field of technology in the new era. On one hand, NASDAQ directed capital into high-tech sectors. Starting from the 1980s, significant breakthroughs were achieved in genetic engineering, the pharmaceutical industry, biotechnology, computers, and telecommunications, among other fields. The rapid development of scientific and technological advancements presented a ripe opportunity, which the agile venture capital industry in the United States captured, investing in high-tech sectors. NASDAQ provided the institutional framework for exiting from venture capital investments. Additionally, NASDAQ offered financial support to small and medium-sized enterprises, effectively encouraging technological innovations.
On the other hand, high technology became a new source of economic growth and promoted the upgrading of traditional industries. The high-tech industry in the United States propelled the country into its longest period of continuous economic growth since World War II. High technology facilitated industrial upgrading, leading not only to increasing output value year after year but also to the informationization and high-tech transformation of traditional industries. It became a new growth point of the US economy and a pillar industry. Consequently, the US economic growth relied on an information industry foundation. The formation and development of the information industry played a critical role in the prosperity and stability of the US economy, acting as the fundamental driving force behind the "new economic structure."
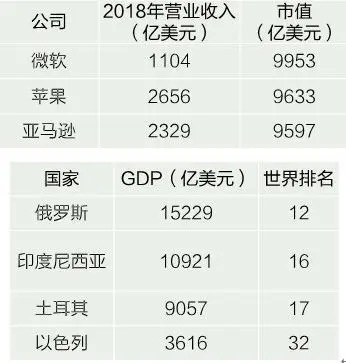
NASDAQ-listed companies such as Microsoft, Apple, and Amazon are enormously wealthy, with market values exceeding twice the GDP of Israel.
Actually, the competition between the United States and Japan provides further evidence. In the 1970s and 1980s, as Japan's economy seemed poised to surpass that of the United States, the game-changer that allowed the United States to pull ahead was the economic transformation brought about by the development of internet technology. In this regard, the Nasdaq played a crucial role by channeling funds into the technology industry. On the other hand, Japan suffered severe policy mistakes in the financial industry. Following the Plaza Accord, Japan faced the dual blow of a burst real estate bubble and trade conflicts, which ultimately dealt a devastating blow to its economy.
Over the past year, the bull market returned, with technology leading the way.
As I said back in October 2024, the rally that began on September 24 was not merely a rebound, but a reversal. Since then, China's capital markets have undergone a broad revaluation, moving from undervaluation toward fair value.
The Shanghai Composite Index reached its highest level in a decade. The "Yi-Zhong-Tian" trio—Eoptolink, Zhongji Innolight and TFC Communication, three prominent Chinese optical communications stocks—saw their share prices multiply severalfold in a single year. Cambricon's market capitalization briefly exceeded RMB 600 billion. Elsewhere in the technology sector, triple-digit price-to-earnings ratios and valuations exceeding RMB 10 billion became commonplace.
Some investors were greedy; others, fearful. Still others asked me: Are technology stocks in a valuation bubble?
My answer is that what we are witnessing is the hunger and anxiety of an era, reflected in the capital markets. Once you understand this, the current fervor for technology investing is no longer difficult to explain.
Investment has nothing to do with macroeconomics, but everything to do with geopolitics.
China-US relations will shape the investment landscape for decades to come. Geopolitics has played a major role in shaping the hunger and anxiety of our times, fundamentally reshaping the way we invest.
What, then, lies at the heart of China's hunger and anxiety?
The Fourth Industrial Revolution is already underway, yet China has not fully overcome the technological shortcomings left by the Third. There is no time to lose.
This is why some people wonder: Why do Chinese computing chip companies command such high valuations when their technologies still lag so far behind NVIDIA's? Why does NVIDIA trade at just 50 times earnings, while a company hailed as "China's answer to NVIDIA" commands a multiple of 300?
To me, this gets the logic exactly backward.
It is precisely because these companies cannot catch up with NVIDIA in the near term that they command a higher strategic premium. The wider the technological gap, the greater the strategic value.
The further something lies beyond our reach, the stronger our hunger. The harder it is to catch up, the deeper our anxiety. If China were to achieve a complete breakthrough in computing chips one day, valuations might actually come down.
Where can one find China's most spectacular natural landscapes?
Much of the answer, I believe, lies in and around the Hengduan Mountains: the Meili Snow Mountains, Jade Dragon Snow Mountain, Mount Gongga, Mount Siguniang, Jiuzhaigou, and many others. Vast differences in elevation and deep fault lines have given rise to landscapes of extraordinary grandeur.
Hard-tech investing follows a similar logic.
Technological gaps, discontinuities in capabilities, and missing links in industrial systems: a leap in difficulty brings a leap in valuation, and a successful breakthrough can, in turn, bring a leap in returns.
This logic extends well beyond computing chips. It is equally evident in memory semiconductors, commercial spaceflight, and other sectors where China still faces substantial technological gaps with other countries.
It was precisely this conviction that led CoStone Capital, starting in 2016, to decisively focus its investments on three areas: hard tech, emerging industries, and life sciences and healthcare. In this context, "hard tech" refers specifically to important industries in which China faces a technological gap with the United States.
Thanks to this forward-looking strategy, CoStone Capital established an early presence across the full value chains of key sectors, including semiconductors, artificial intelligence, and robotics.
Looking ahead, the frontiers of technological progress and industrial upgrading are boundless. Nor can the gaps in hard technology be closed overnight. The twin windows of opportunity presented by technological innovation and the development of homegrown alternatives to foreign technologies have only just begun to open.
The road ahead is long, but the future holds immense promise.
As an investment firm, CoStone Capital will continue to invest where the hunger and anxiety of each era run deepest, move forward with the tensions that shape our times, and extend our reach toward the most challenging—and most important—frontiers.
Spring 2026