
In the interview, Zhang Wei criticized the fraudulent innovation of Luckin Coffee and pointed out its incompetence in operational abilities.
READ
"China possesses a huge market and much leeway with substantial opportunities. China, where you can definitely make a fortune.”
READ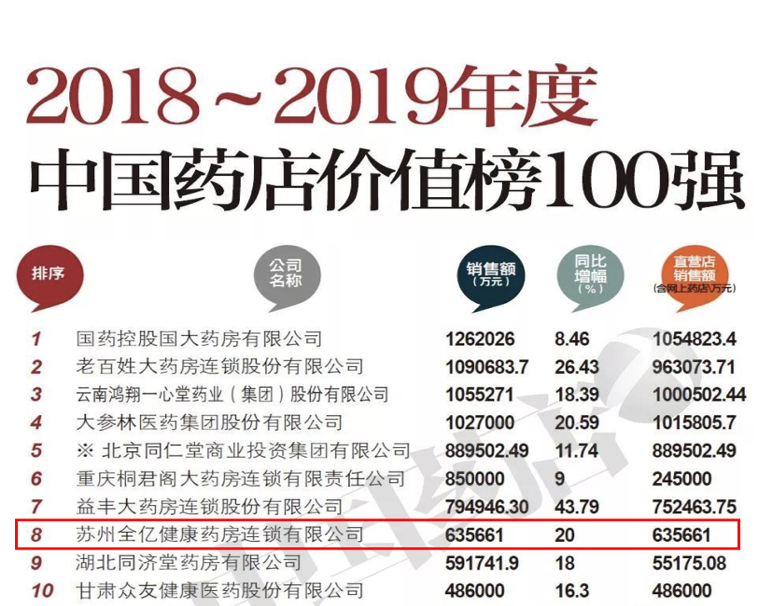
As a startup established in 2016, Suzhou PharmPlus Pharmacy Chain Co., Ltd. 苏州全亿健康药房连锁有限公司 (hereinafter referred to as “PharmPlus”) has achieved an “atypical growth” of 6 billion yuan in turnover in just three years.
READ
“So, it is easy for companies like Alibaba and Tencent to take off in a short time and become one of the world leaders. But it is difficult for hard tech companies in China. Therefore, the success of HUAWEI is bigger.” Zhang Wei added.
READ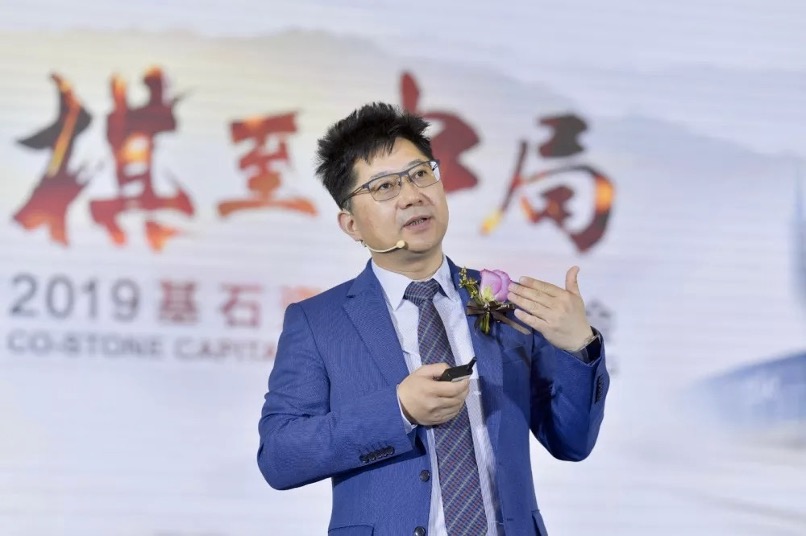
On CoStone Capital’s annual conference on April 28th, CoStone Capital Zhang Wei provided a perspective that the upcoming Sci-tech Innovation Board (STAR Market) is another great practice of asymmetric competition in China’s capital market.
READ
In the interview, Zhang Wei criticized the unwise investment on the trendy projects and reiterated that he remained bearish in projects like NEVs and bicycle sharing.
READ
In a recent week, many listed companies had disclosed massive losses in quite a ridiculous way. Seriously speaking, that was a real embarrassment to China’s capital market.
READ
China Securities Regulatory Commission (CSRC) says it’s pushing ahead with the reform and opening-up of the capital market by accelerating the pilot program of Shanghai’s Science and Technology Innovation Board, also known as the STAR Market. CoStone Zhang Wei published an article on the Nasdaq-style STAR Market in Securities Times. The article is as follows:
READ
Recently, to relive share pledge crisis for listed companies, lots of “bailout funds” have come up in the market, drawing much attention and discussion.
READ
CoStone Capital started its engagement in buyouts in 2004. After nearly 15 years of practice, it has gradually fashioned its own principles: only invest in familiar fields, tie itself closely to the company’s management team, get highly involved in corporate operations, and obtain more benefits beyond efficiency improvement through industry collaboration.
READOver the past year, the bull market returned, with technology leading the way.
As I said back in October 2024, the rally that began on September 24 was not merely a rebound, but a reversal. Since then, China's capital markets have undergone a broad revaluation, moving from undervaluation toward fair value.
The Shanghai Composite Index reached its highest level in a decade. The "Yi-Zhong-Tian" trio—Eoptolink, Zhongji Innolight and TFC Communication, three prominent Chinese optical communications stocks—saw their share prices multiply severalfold in a single year. Cambricon's market capitalization briefly exceeded RMB 600 billion. Elsewhere in the technology sector, triple-digit price-to-earnings ratios and valuations exceeding RMB 10 billion became commonplace.
Some investors were greedy; others, fearful. Still others asked me: Are technology stocks in a valuation bubble?
My answer is that what we are witnessing is the hunger and anxiety of an era, reflected in the capital markets. Once you understand this, the current fervor for technology investing is no longer difficult to explain.
Investment has nothing to do with macroeconomics, but everything to do with geopolitics.
China-US relations will shape the investment landscape for decades to come. Geopolitics has played a major role in shaping the hunger and anxiety of our times, fundamentally reshaping the way we invest.
What, then, lies at the heart of China's hunger and anxiety?
The Fourth Industrial Revolution is already underway, yet China has not fully overcome the technological shortcomings left by the Third. There is no time to lose.
This is why some people wonder: Why do Chinese computing chip companies command such high valuations when their technologies still lag so far behind NVIDIA's? Why does NVIDIA trade at just 50 times earnings, while a company hailed as "China's answer to NVIDIA" commands a multiple of 300?
To me, this gets the logic exactly backward.
It is precisely because these companies cannot catch up with NVIDIA in the near term that they command a higher strategic premium. The wider the technological gap, the greater the strategic value.
The further something lies beyond our reach, the stronger our hunger. The harder it is to catch up, the deeper our anxiety. If China were to achieve a complete breakthrough in computing chips one day, valuations might actually come down.
Where can one find China's most spectacular natural landscapes?
Much of the answer, I believe, lies in and around the Hengduan Mountains: the Meili Snow Mountains, Jade Dragon Snow Mountain, Mount Gongga, Mount Siguniang, Jiuzhaigou, and many others. Vast differences in elevation and deep fault lines have given rise to landscapes of extraordinary grandeur.
Hard-tech investing follows a similar logic.
Technological gaps, discontinuities in capabilities, and missing links in industrial systems: a leap in difficulty brings a leap in valuation, and a successful breakthrough can, in turn, bring a leap in returns.
This logic extends well beyond computing chips. It is equally evident in memory semiconductors, commercial spaceflight, and other sectors where China still faces substantial technological gaps with other countries.
It was precisely this conviction that led CoStone Capital, starting in 2016, to decisively focus its investments on three areas: hard tech, emerging industries, and life sciences and healthcare. In this context, "hard tech" refers specifically to important industries in which China faces a technological gap with the United States.
Thanks to this forward-looking strategy, CoStone Capital established an early presence across the full value chains of key sectors, including semiconductors, artificial intelligence, and robotics.
Looking ahead, the frontiers of technological progress and industrial upgrading are boundless. Nor can the gaps in hard technology be closed overnight. The twin windows of opportunity presented by technological innovation and the development of homegrown alternatives to foreign technologies have only just begun to open.
The road ahead is long, but the future holds immense promise.
As an investment firm, CoStone Capital will continue to invest where the hunger and anxiety of each era run deepest, move forward with the tensions that shape our times, and extend our reach toward the most challenging—and most important—frontiers.
Spring 2026